
Most first-time condominium homebuyers spend 90 percent of their time looking at the 10 percent of the building they actually own: inside their unit.
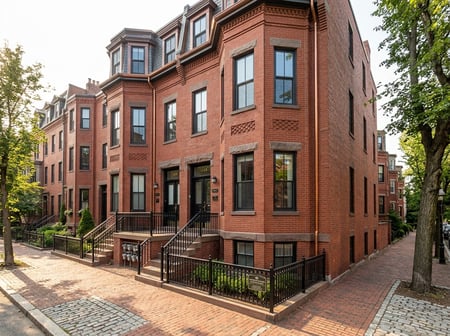 In Greater Boston’s older real estate market, surprised homebuyers often find the real costs elsewhere. Two of the biggest condo buyer frustrations are unexpected special assessments and poor association management.
It’s critical to take a three-dimensional approach to evaluating whether to buy a particular condominium. Why? It’s because a beautiful kitchen can’t protect you from a $20,000 special assessment for brick pointing.
Buying a Boston Condo
Purchasing a residential property in Boston or surrounding communities often comes down to choosing between a standalone or attached single-family house and a condominium. While single-family ownership grants complete autonomy and sole responsibility for repairs, buying a condominium means purchasing private interior space while entering a binding legal and financial partnership with co-owners for the rest of the building.
The Greater Boston condominium market is defined by historic brownstones, converted triple-deckers, and modern developments, so evaluating only the interior finishes overlooks critical liabilities. First-time homebuyers (and all homebuyers) must evaluate three distinct dimensions before buying.
Dimension 1: The Private Unit (“Studs-In”)
In a condominium, private ownership typically extends from the interior drywall inward. A standard home inspection evaluates the private mechanical systems, appliances, plumbing fixtures, and interior electrical components. Buyers must verify the unit's legal boundaries, using the Master Deed to determine whether high-cost components, such as exterior doors, windows, private decks, and HVAC, are the owner’s responsibility or categorized as common elements and systems maintained by the association. Condominium rules vary and determine your responsibilities.
Dimension 2: Common Elements and Shared Maintenance
Condo owners hold an undivided percentage interest in the building’s common components. In Greater Boston’s older housing stock, deferred critical maintenance may create major financial exposure:
- Masonry and Repointing: Historic brick facades require periodic mortar repointing, which can cost tens of thousands of dollars per unit if neglected for many years.
- Shared Infrastructure: Roof replacements, parking lot paving, and shared boilers are shared liabilities funded by unit owners. Ask when these items are due for repair or replacement.
- Self-Managed Associations: Smaller two- and three-unit conversions typically lack professional property management, requiring owners to personally manage snow removal, landscaping, contractor negotiations, and other association business. Professional property management costs more, but it also offers significant convenience. Which is more important to you?
Dimension 3: Financial Health and Governing Documents
What is a condominium? Under Massachusetts General Laws Chapter 183A, condominiums are governed by a Master Deed, Declaration of Trust, and Bylaws. Due diligence requires careful review of these documents and the association’s business operations:
- Capital Reserves: Fannie Mae and Freddie Mac generally require associations to allocate at least 10 percent of their annual operating budget to a reserve account. That amount will increase to 15 percent in January 2027. A professional reserve study details whether accumulated funds align with upcoming capital replacements. Not all homeowners associations have a comprehensive study, and many smaller associations keep only the minimum required reserves.
- Special Assessments: When reserves cannot cover major repairs, the association levies a special assessment on all owners. Reviewing 12 to 24 months of meeting minutes identifies recurring system issues or pending votes on unbudgeted projects. Simply asking the seller whether there are any ongoing or anticipated special assessments is a good start. Larger associations sometimes have an owner newsletter with useful information.
- The 6(d) Certificate: Massachusetts law requires a clean 6(d) certificate at closing to certify that the seller owes no outstanding common fees or municipal assessments. Be sure to verify whether or not the seller will pay off any ongoing special assessment at or before closing.
Essential Questions for the Listing Agent Before Buying a Condo
Before submitting an offer, prospective homebuyers should request written answers to these four primary questions:
- What percentage of annual dues is transferred into the capital reserve account, how much is in the account, and what percentage of the budget does it represent?
- Are there any capital repair projects or special assessments planned within the next 24 months? If so, when and what’s the anticipated cost?
- What is the current owner-occupancy percentage?
- Are parking spaces and storage lockers deeded, assigned, or first-come, first-served?
Keep in mind that your lender will likely request the homeowners association complete a condo questionnaire. The answers to the lender’s questions may determine whether you qualify for a home loan.
Conclusion
Navigating a condominium purchase in Boston and surrounding areas requires balancing the unit's visual appeal with thorough due diligence.
Put together a team that will advocate for you. Start with a loyal buyer agent. Work with a loan officer experienced in helping condo buyers, patient with first-time homebuyers, and willing to explain all your lending options. Your real estate attorney will review and explain the Master Deed, Declaration of Trust, Bylaws, and financials. Your insurance agent will make sure you have adequate coverage.
Verifying an association's fiscal health and maintenance plans ensures that your new home remains a predictable, stable investment rather than a source of unexpected liabilities and headaches.